The administration of this trading intermediary asserts its credentials regarding reliability, technological sophistication, and operational security. Promotional materials distributed by management highlight additional features, such as software access and purported regulation by the CNAD commission. Despite aggressive marketing and promotion, the project in reality holds merely a restricted license — one that does not grant the legal right to function as a trading intermediary. Furthermore, the entity maintains a superficial legal registration not only offshore but also within the territory of the United States. In this Solonix.one review, we wonder whether engaging with the firm is genuinely safe or fraught with risk.
Contents
- Key Points to Know
- What Stands Out About the Solonix.one Website?
- Inside the Offshore Registration of Solonix.one
- Trading Conditions Explained
- Checking Compliance with Legitimate Rules
- How Long Has Solonix.one Really Been Around?
- Platform and Support Overview
- Online Reputation: What We Found
- Conclusion: Risks and Reliability of Solonix.one
- Sources
Key Points to Know
| Main Website | https://solonix.one/en |
| Additional Domains | https://client.solonix.one/en/register |
| Online Since | 2025 |
| Legal Entity Name | Digital Trading Group of Central America, S.A. de C.V. |
| Pretended to Be Regulated | CNAD |
| Fact-Checked Regulation | CNAD (PSAD-0063) |
| Deposit to Start Trade | No Limit |
| Leverage up To | Unknown |
| Spreads From | Undisclosed |
What Stands Out About the Solonix.one Website?
-
Contact details have been published.
-
The project holds a restricted license from the regulator.
-
The platform is incorporated as a legal entity in offshore jurisdictions.
-
Negative and critical feedback from clients.
-
Restricted access to the website alongside periodic connection issues.
-
Information regarding spreads and leverage remains undisclosed.
Inside the Offshore Registration of Solonix.one
The trading intermediary holds legal registration across various jurisdictions, a fact repeatedly communicated to platform clients via the official website’s footer. The corporate structure, which spans the UAE, El Salvador, the US, Costa Rica, and Saint Lucia, appears solid and at the same time completely accurate. The owners even provide active links to the CNAD and FinCEN registries, where one can verify the validity of the permits.
At the same time, the Terms and Conditions state that the managing company for Solonix.one is exclusively DIGITAL TRADING GROUP OF CENTRAL AMERICA, S.A. DE C.V. and any disputes will be resolved in the jurisdiction of El Salvador.
The operating company’s location in El Salvador grants the platform legal status as a digital asset service provider (DASP) under the supervision of the CNAD and a zero-tax regime. However, this jurisdiction primarily regulates crypto services and does not provide the level of protection for investors’ funds typical of European or UK financial regulators (CySEC, FCA). Regarding dispute resolution, El Salvador has a civil law system, and legal proceedings are conducted strictly in Spanish. For a foreign client, filing a claim or having foreign court decisions recognized in El Salvadoran jurisdiction poses significant legal hurdles.
Trading Conditions Explained
In this Solonix.one review, it is essential to examine the transaction conditions offered on the platform. Following account registration — specifically within the account comparison table — details regarding account types are presented, granting access to Standard, Gold, and Institutional tiers. In this manner, information regarding the available financial instruments is disclosed, alongside an emphasis on available supplementary services. Below, we will discuss the assets, starting deposit requirements, leverage, commissions, and related parameters. This will help prospective clients gain a clearer understanding of the broker prior to any potential collaboration.
The Solonix.one project focuses primarily on basic crypto pairs, providing access to BTC/USDT, SOL/USDT, and ETH/USDT markets. As observed in practice, the actual selection of financial instruments is extremely limited, if not minimal. We decide that this stems not only from restricted regulatory oversight, but also from the deliberate policy of a dubious broker.
To initiate a partnership with Solonix.one, one must fund the account with a minimum allowable deposit — though no strict limits are established in this regard. This flexibility exists because the platform relies heavily on cryptocurrency for transaction processing, meaning deposit thresholds are non-existent; even a five-dollar transfer is permitted. Nevertheless, we advise against depositing any funds whatsoever, as it remains fundamentally unsafe. The likelihood of losing invested capital is exceptionally high.
Margin trading is likewise supported on the Solonix.one platform. Crucially, the leverage ratio is left unspecified, which once again creates constraints for users and opens the door to scenarios where elevated leverage can be imposed via a manipulated trading terminal. In fact, for an unlicensed project (as no brokerage license exists), nothing prevents the firm from setting leverage ratios as high as 1:1000 — a common occurrence among fraudulent outfits.
Management promises 24/7 client support, claiming the availability of dedicated account managers, API access, and supplementary trading accounts. Within the educational materials, only a highly restricted FAQ section is provided. There is no opportunity whatsoever to study dedicated literature or structured instructional content.
Checking Compliance with Legitimate Rules
The Solonix.one broker requires a thorough verification of its regulatory status — we have already addressed its corporate registration earlier. Next, we wonder how it’s licensing holds up under closer examination, alongside the physical location of its head office and the prospects of fund recovery, including through professional legal representation.
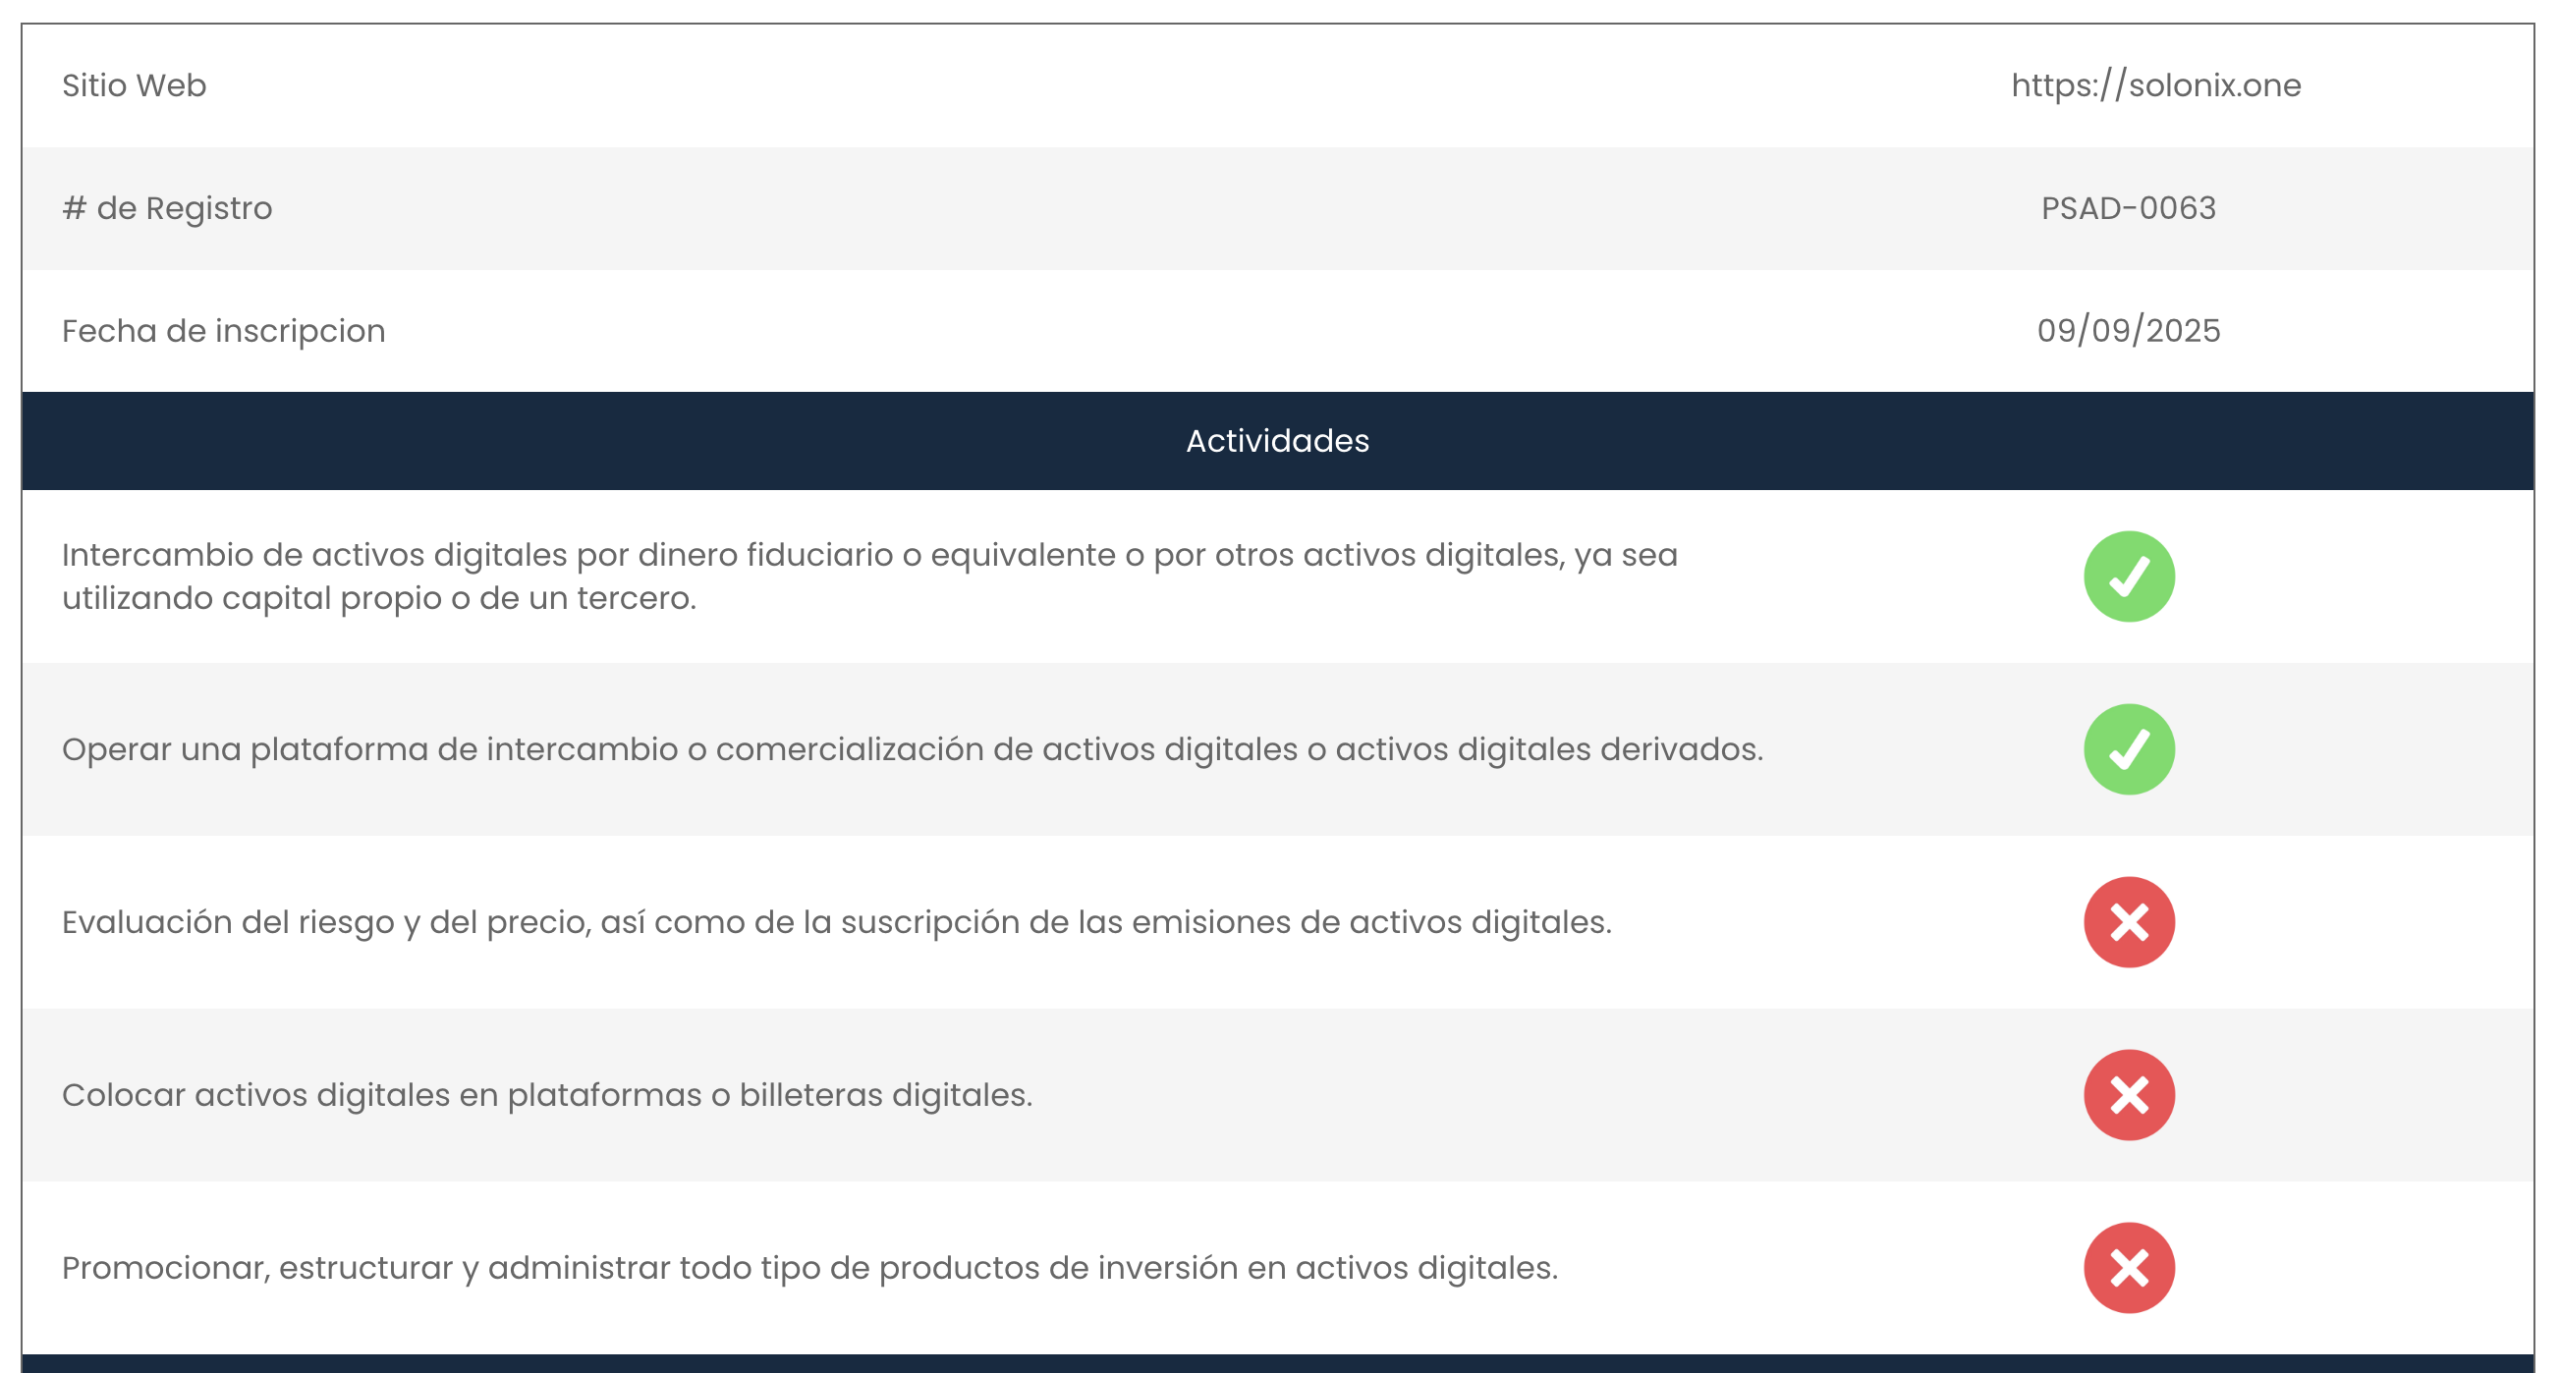
On the official website of the Solonix.one brand, numerous assertions regarding licensing are made, supported by a direct link to the regulatory register of El Salvador. This might appear reassuring on the surface, but in practice, a firm holding such a permit has no legal right to operate as a broker or investment intermediary.
No genuine details regarding a physical representative office exist, as the firm simply operates without physical premises. The entity maintains a policy of secrecy; thus, only details concerning its restricted license and legal registration are disclosed. Moreover, all platform transactions are conducted strictly in cryptocurrency, while details regarding management and staff remain completely undisclosed. The confluence of these factors serves as an unambiguous red flag, confirming once again why working with this brand is unsafe.
How Long Has Solonix.one Really Been Around?
The operational lifespan of a trading intermediary is no less significant than its regulatory and legal status. A company operating for over five years typically accumulates a substantial body of client reviews and expert analysis. Such materials frequently detail the firm’s operational characteristics in full, allowing one to determine whether collaboration is viable.
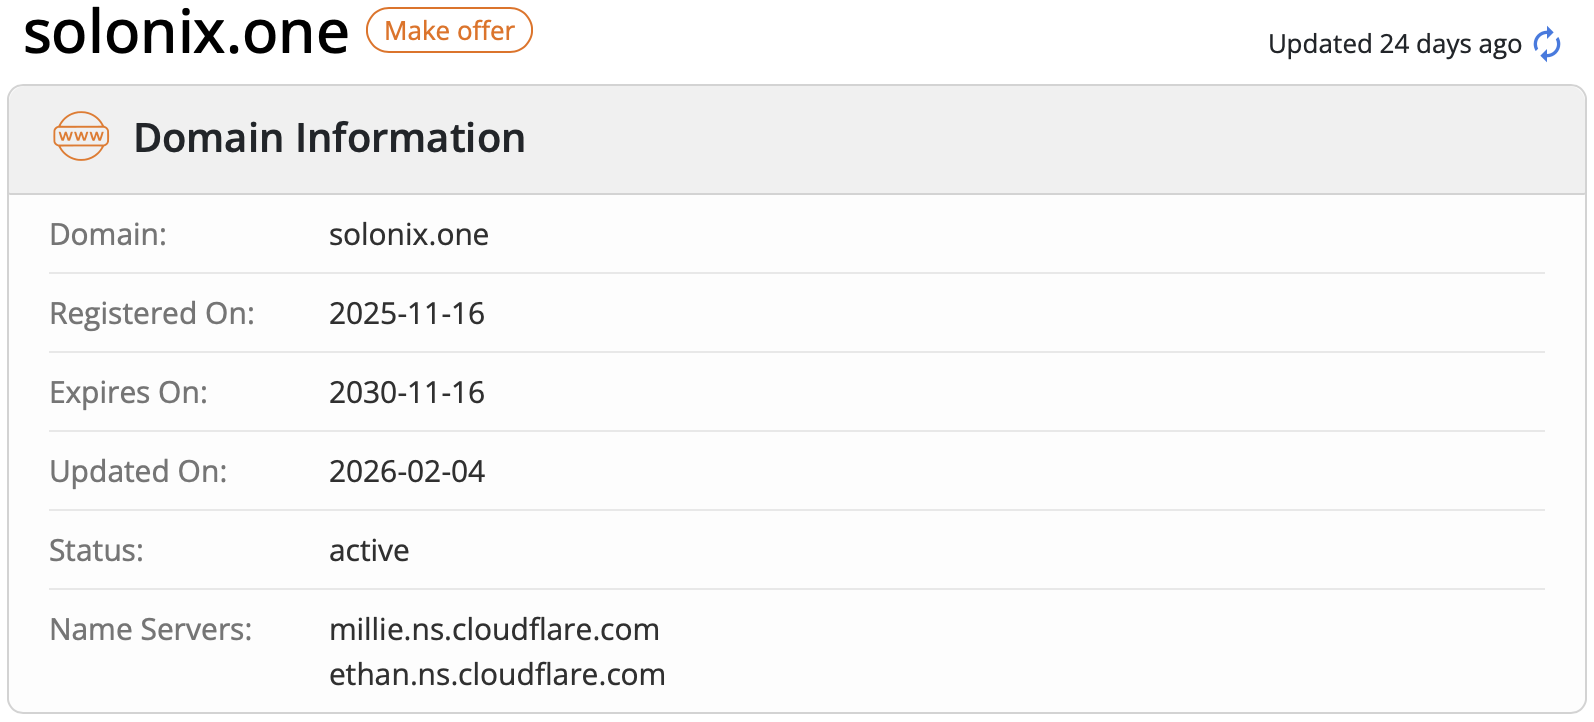
Ascertaining the actual tenure of the Solonix.one platform is straightforward — one need only verify its domain name. Checking the domain via WHOIS and WebArchive services reveals the true launch date. In reality, the trading intermediary has only been active since late 2025, with real operations commencing in 2026. Therefore, it comes as no surprise that genuine customer reviews are minimal, and comprehensive analytical overviews are entirely absent.
Platform and Support Overview
The Solonix.one trading platform is a browser-based terminal with severely restricted functionality. While the account table mentions access to various software iterations — including portable and desktop versions — the official website provides no active download links for these applications, serving as a clear warning sign of unreliability. In practice, proprietary terminals provided by unvetted brokers are controlled internally to systematically drain a trader’s balance to zero. Beyond issues such as non-existent liquidity, there are significant concerns regarding the operational stability of the terminal itself.
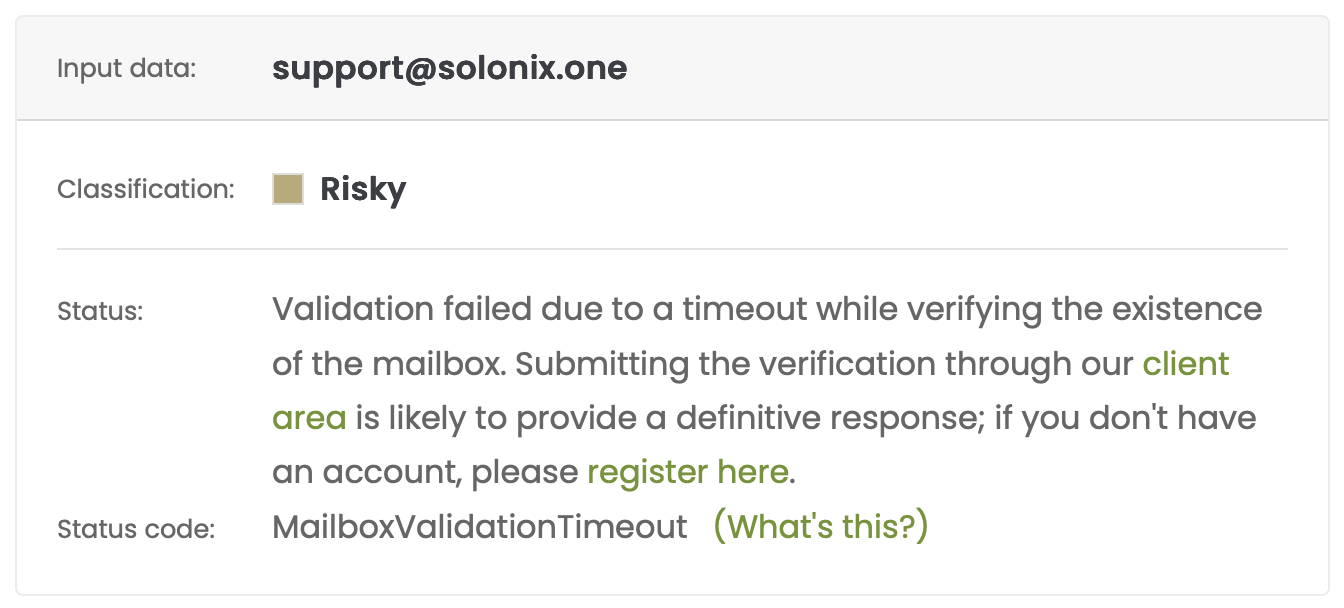
Customer support at Solonix.one is conducted in an exceedingly primitive manner. Contact details for reaching support are listed in the appropriate section, but communicating via email carries risk — a fact confirmed by basic email validation checks. Consequently, expecting quality service would be misguided. Furthermore, the official website lacks a live chat feature. While social media links are referenced, opening the firm’s page with 8 followers on X immediately reveals how “popular” the company truly is within the trading community.
Online Reputation: What We Found
The reputation of the trading intermediary Solonix.one within the community is quite contradictory. The volume of authentic client feedback approaches zero. Conversely, several rudimentary paid reviews — written to a single boilerplate brief — are actively circulated. The underlying message of these commissioned articles is simple: emphasizing the firm’s reliability, its license, and its trading tools. However, these pieces conveniently omit its restricted licensing status and offshore incorporation.
Conclusion: Risks and Reliability of Solonix.one
We advise against any form of cooperation with this broker. The project possesses no legal mandate to function as a trading or investment intermediary. The platform relies on primitive, commissioned reviews, while core trading parameters — including leverage, spreads, and commissions — are intentionally concealed. In practice, a manipulated terminal is used to conduct trades, leaving clients at a severe disadvantage.


03.10.2026 at 00:00
Who in the crypto community has heard of Solonix?
This company exhibits a clear lack of genuine reviews… so, based on my trading experience, I do not recommend cooperating with the firm. They conceal their key trading parameters and employ a manipulated, feature-restricted terminal for market operations. And client support is delivered in a very primitive fashion, making direct contact with support staff notably difficult.